Press ESC to close

Why CIBIL Score Is Important for Personal Loan Approval

Getting a personal loan or a credit card is only possible when you have a good income and a CIBIL score, and it is decided based on your transactional history. However, there is a certain range of credit scores, and depending on the lender’s policy. Generally, it depends on your personal loan borrowing frequency and repayment. So, if you are planning to apply for a personal loan or credit card, always check your CIBIL score, match your eligibility and get the loan without any additional difficulties. In a brief discussion, let’s understand why the CIBIL Score Is Important, especially for personal loans and credit scores. 

What is a CIBIL score?

CIBIL score is a transactional history which is calculated based on your transactional history, especially when you apply for a loan or use your credit card, with an appropriate credit score, like maximum up to 30% of your credit limit. Since there are multiple credit bureaus like TransUnion, CIBIL, Experian Credit Information Company of India, Equifax Credit Information Services, and CRIF High Mark Credit Information Services. 

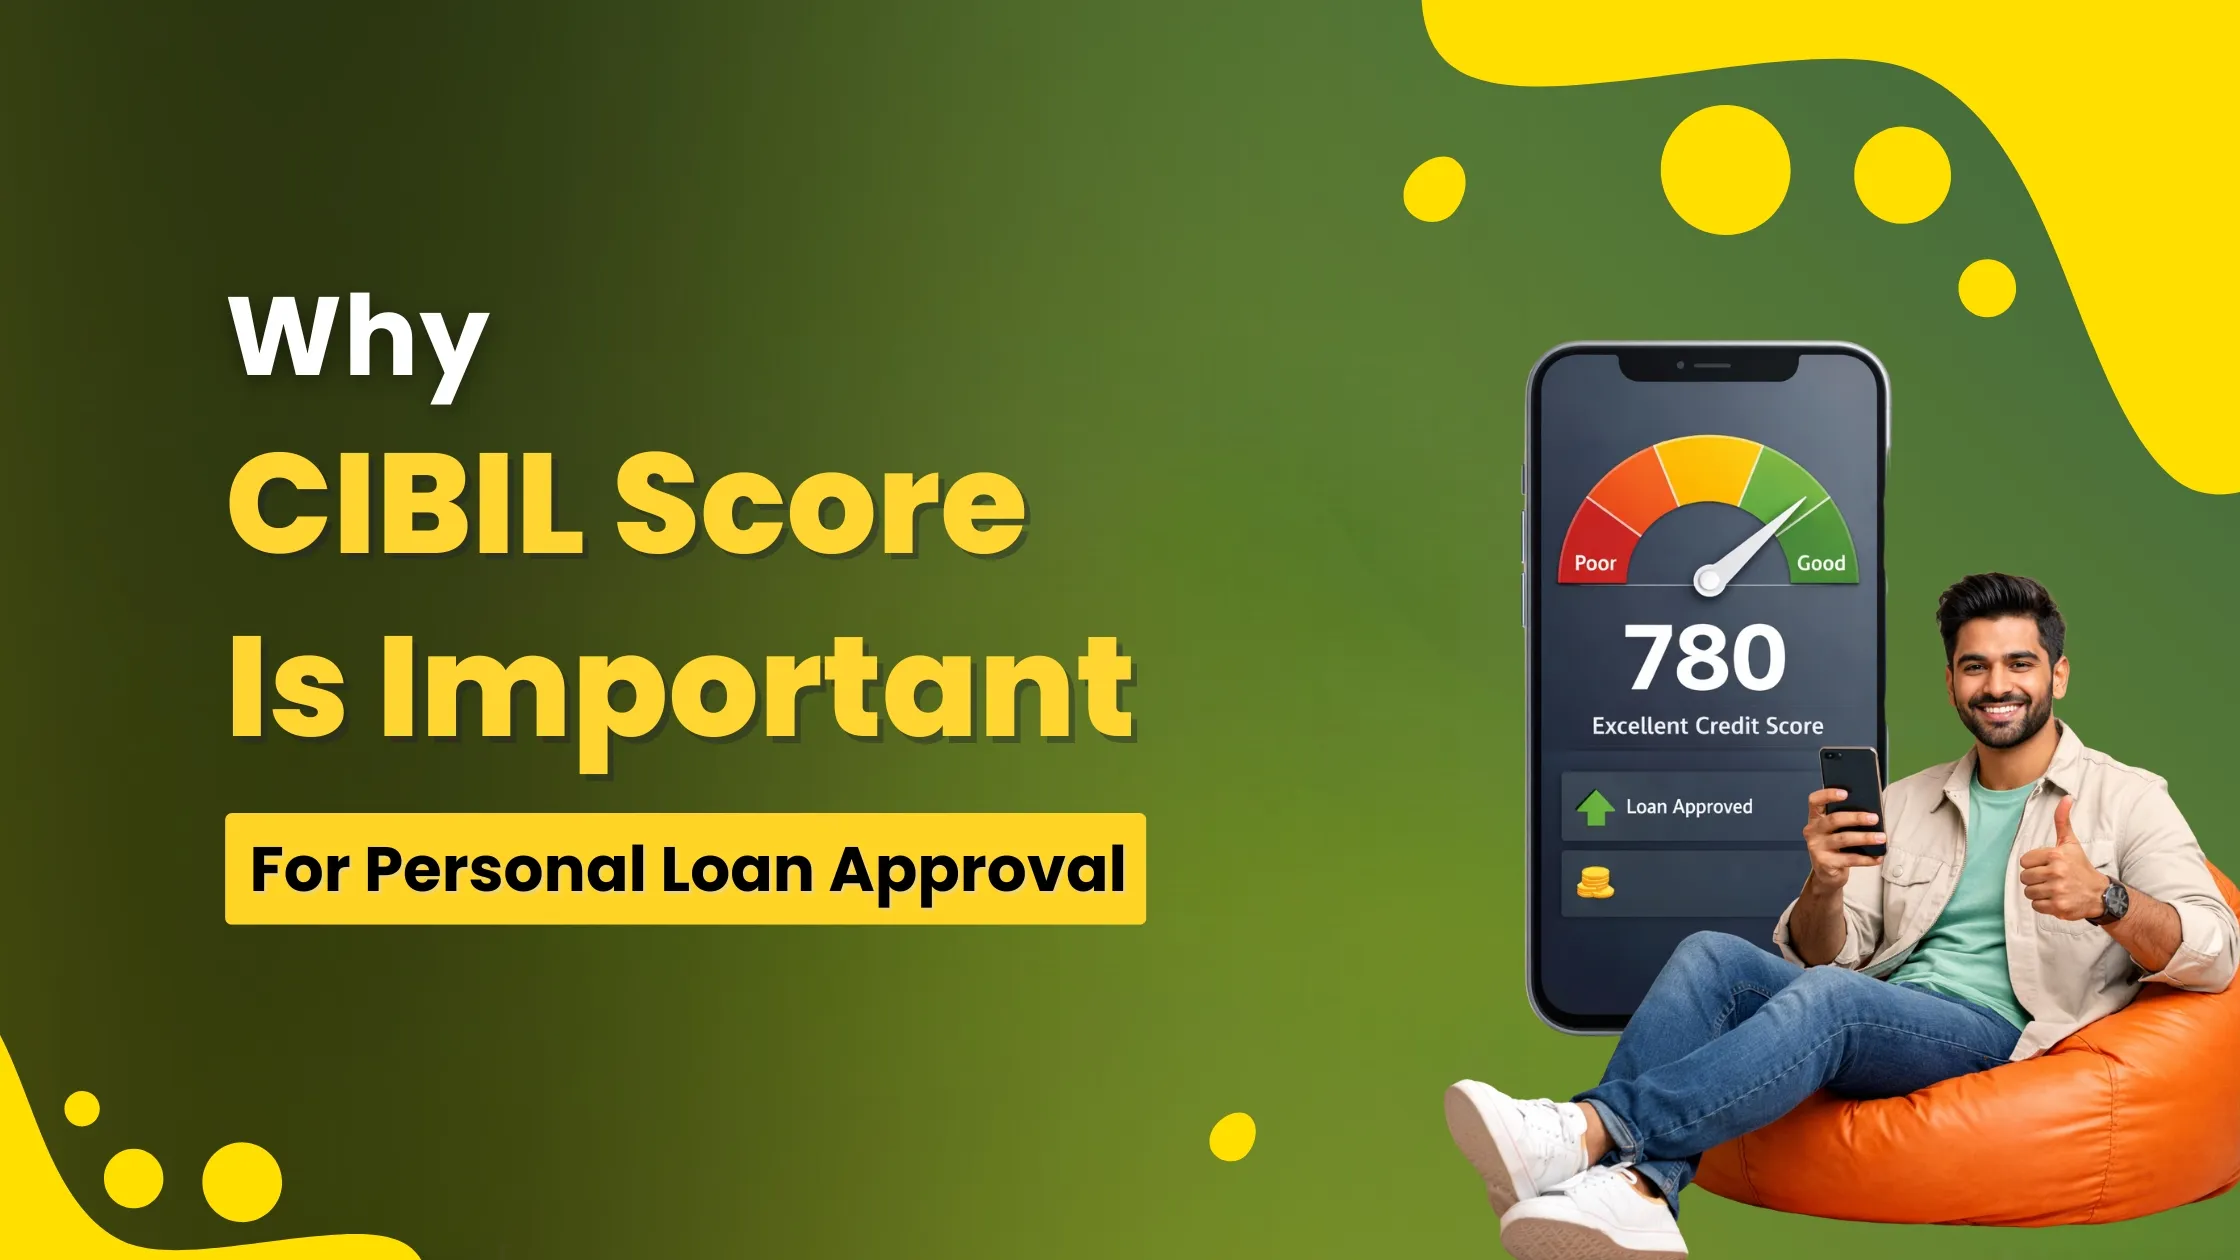
Where the TransUnion CIBIL score range from 300 to 549 is considered Poor. The range from 550 to 649 is Fair and considerable. 650–749 is Good, and finally, 750 to 900 is known as Excellent. However, the loan is approved considering different terms and conditions as well.  

Consequences of a low CIBIL Score

While getting a personal loan, a low CIBIL score can always create difficulties, because you can face difficulties like rejection of the loan, a higher interest rate, a higher premium of insurance and all:

1. Loan application rejection: The loan application can be rejected when applying with a low CIBIL score. When you apply with a CIBIL score, the lenders do not approve your personal loan or credit card application. 

2. Higher interest rate: Even after the approval, the personal loan interest rate can be higher when applying with a low CIBIL score. 

3. Lower loan or credit limit: While applying with a lower interest rate, the approved loan amount and credit limit can be lower.

4. Strict eligibility criteria: When your CIBIL score is low, the lender can check all the documents strictly, and then you can face rejection and other difficulties. 

5. Difficulty getting credit cards: When you apply for a credit card, you can face rejection if your CIBIL score is low. However, if you have an average score, but your income is good, you can get a credit card, which can help you enhance your score.

6. Delayed loan approvals: The loan approval time can be longer, which can lead to multiple difficulties. 
How to Apply for a Small Cash Loan on an Aadhaar Card

To apply for a small cash loan on Aadhaar card, you need to go to the application or lending page, which you can reach by clicking the Apply Now button, especially on the website you are willing to apply to. So, to apply for the personal loan, you can fill in all the details in the application form, like the loan amount, and all. And upload your documents, especially the Aadhaar. Once you have completed the loan application, it is approved after checking all the details, and it is disbursed. To apply for a personal loan, follow the steps. 

1. Go to the website and the Application page

2. With all the required details, fill in the Application form.

3. Upload your documents like Aadhaar and PAN card. 

4. Get the response from the executive and get the verification and approval.

5. Once approved, get the disbursal of the personal loan amount. 

6. Use the loan amount and repay as per the tenure 

How to enhance your CIBIL score

If your CIBIL score is below average and you are facing difficulties, you can increase your CIBIL score by using some specific techniques. And, some specific strategies that can help you enhance your CIBIL score are as follows:  

1. Apply for a lower loan amount: To enhance your approval chances, you must apply for the loan within your limit. As per the eligibility and income ratio, you can apply. Because when you apply for the loan, the lender always checks your eligibility and credit score.  

2. Use your Credit Limit below 30%: It is always suggested to use the credit limit below 30% because using a higher limit can affect your credit score. 

3. Repay the loan amount on time: You must repay all types of EMI on time, which can help you enhance your credit score for enhancing the financial chances in future. 

Read this blog as well: How to Close Personal Loan Early

Conclusion

If you are still planning to apply for a personal loan and are struggling due to a lower CIBIL score, you can apply for the loan through a website which is registered and accepts the loan application even after a low CIBIL score. So, to apply for a loan, just check your eligibility, match it with all the terms and conditions, and finally apply for the loan easily. As per the suggested strategy, especially after knowing the facts that Why CIBIL Score Is Important, you can proceed with the positive strategy. It will not only help you get the loan on time, but it will also improve your credit score over time.  

Frequently Asked Questions (FAQ)

Why is a CIBIL score important for personal loan approval?

A CIBIL score always helps lenders to evaluate your creditworthiness, depending on your transactional and repayment history. And, if it is higher, your chances of getting approval become higher.

Most of the lenders consider a CIBIL score of 700 or above as a good score for personal loan approval. But a  score above 750 is considered excellent, and it always increases the chances of approval.

If your CIBIL score is low, it can lead to loan rejection, higher interest rates, lower loan amounts, and multiple difficulties in getting credit cards.

Yes, many lenders approve a small cash loan based on your Aadhaar card along with basic documents like PAN card and personal details, which must be submitted while accomplishing online application process.

You can improve your CIBIL score with a simple strategy, such as paying all your EMIs on time. Keep your credit card usage below 30% of the maximum approved limit.

Disclaimer

This article is for informational purposes only and does not constitute financial advice. Loan foreclosure policies, prepayment charges, and CIBIL score impacts vary depending on the lender and individual financial profile. Readers are advised to consult their bank, NBFC, or certified financial advisor before making any loan repayment or foreclosure decision. The examples provided are hypothetical and for educational reference only. Loan approval and credit score improvements are subject to eligibility criteria and credit bureau reporting policies applicable in India.

Author

  • Finance Expert

    Saurabh Jha is a technical graduate and seasoned writer, and he has been working as a content writer and research scholar. With more than five years of writing experience in fintech, finance, arts and humanities.

Saurabh Jha

Saurabh Jha is a technical graduate and seasoned writer, and he has been working as a content writer and research scholar. With more than five years of writing experience in fintech, finance, arts and humanities.

Leave a Reply

Your email address will not be published. Required fields are marked *